

EarnIn: Why Wait for Payday?

- 140.53K Reviews
- 4.8
- Downloads
- 10,000,000+
Our take on EarnIn: Why Wait for Payday? from Appgk
Waiting for payday is one of those small financial pressures that can make an ordinary week feel much harder. A bill arrives early, a tank needs filling, or a grocery trip costs more than expected, while the money I have already earned remains tied to the usual pay schedule. EarnIn is designed for that gap. It is a free finance app from Activehours Inc. that lets eligible users access part of their earned pay before payday, with the store summary describing advances of up to $150 a day and a maximum of $1,000 per pay period.
After spending time looking at how the app fits into real money routines, I see it as a short-term cash-flow tool rather than a complete budgeting solution. That distinction matters. It can be useful when the timing of income is the problem, but it does not make an unaffordable expense affordable. My overall view is positive but careful: EarnIn works best when it solves a one-off timing problem and the repayment date is already clear.
What EarnIn is really useful for
The basic idea is straightforward. Instead of waiting for an employer’s normal payday, a user may request access to money they have already earned, subject to the app’s eligibility and account requirements. The appeal is easy to understand: there is no need to turn a minor shortfall into a long-term borrowing decision when the next paycheck is close and predictable.
In practice, I would think of it as a bridge between two known points in a pay cycle. For example, imagine that my car needs an unexpected repair on a Tuesday, my next paycheck is due soon, and I know exactly how much room remains after rent and other scheduled expenses. An early advance could help me handle the repair without using a credit card balance that might linger. The important part is not simply getting the money; it is knowing what the next paycheck will look like after using the service.
Best Parts of EarnIn: Why Wait for Payday?
Things to Keep in Mind About EarnIn: Why Wait for Payday?
The app has a strong public footprint. It holds an average rating of 4.8 from around 303,000 ratings, with roughly 141,000 written reviews and more than 10 million installs. Those figures do not prove that every user will have the same experience, but they do show that EarnIn is not an obscure experiment with a tiny audience. The developer is Activehours Inc., and the app has been available since January 21, 2014.
It is also free to install and carries an Everyone content rating, which makes the initial barrier low. That should not be confused with free money. A financial app can be free to download while still involving choices, eligibility conditions, optional charges, account connections, or consequences that deserve attention. I would read each screen carefully rather than tapping through setup as quickly as possible.
News and Features Related to EarnIn: Why Wait for Payday?

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Trust starts with the choices shown on screen
For a cash-advance app, trust is less about a polished interface and more about whether I can understand what I am authorizing. I want to know the amount being requested, when it will arrive, how it affects the next paycheck, and whether any optional service or faster delivery choice changes the cost. EarnIn should be judged by that practical clarity, not just by its friendly presentation.
One useful habit is to pause before confirming an advance and write down three things: the amount received, the expected repayment or deduction timing, and the remaining money needed for fixed bills. This simple check guards against a common mistake with early-pay tools: treating tomorrow’s income as spare money when it is already committed to something else.
Don't want to read the full review?
I also prefer to keep account controls deliberate. If the app asks me to connect employment, income, bank, or payment information during setup, I would verify why each connection is needed and whether it can be changed later. I would use the app’s visible settings and account-management screens rather than assuming that deleting the app removes every relationship or authorization. That is not a criticism unique to EarnIn; it is a sensible rule for any service handling financial information.
Where the app fits better than ordinary alternatives
Compared with a credit card, an earned-pay advance can be more appropriate for someone who needs a small, short-lived bridge and wants to avoid revolving a balance. A credit card may be more flexible for a larger purchase or a situation where repayment timing is uncertain, but that flexibility can become expensive if the balance remains unpaid. EarnIn is narrower: it is tied to the user’s pay cycle, which can be helpful because the intended repayment point is easier to identify.
Screenshots
Compared with a traditional personal loan, the app is aimed at a much more immediate problem. A personal loan may offer a structured repayment plan for a larger expense, while an early-pay service is better suited to a short gap. I would not use EarnIn to cover a recurring deficit that appears every month. If rent, utilities, or groceries are regularly unaffordable before payday, repeatedly moving pay forward can hide the underlying problem and leave less money available in the next cycle.
Compared with overdraft protection, the advantage is that I can make a planned decision before a payment fails. The disadvantage is that I must still manage the next paycheck carefully. Overdraft coverage may be automatic in some banking arrangements, while EarnIn requires more active planning. For me, that extra step is a benefit when it makes the decision visible, but it may feel inconvenient to someone seeking a completely automatic safety net.
Small workflow decisions make a big difference
The first non-obvious lesson is to use the app only after checking the entire pay-period calendar, not just today’s bank balance. I would list rent, subscriptions, loan payments, transport, food, and any irregular expense due before the next paycheck. Then I would decide whether the advance solves a genuine timing issue or simply creates a larger shortage later.
The second is to request the smallest amount that solves the immediate problem. The maximum available is not a target. If a smaller advance covers the repair, prescription, or essential purchase, taking less preserves more of the next paycheck. This is especially important because the store summary presents both a daily limit and a pay-period limit; those boundaries describe availability, not what I should borrow.
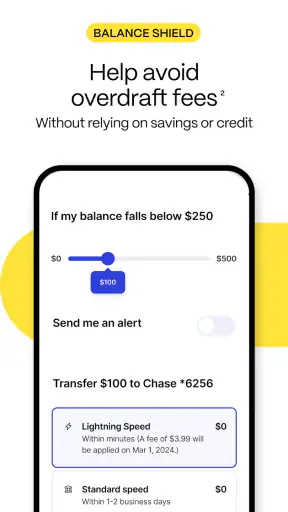
The third is to treat delivery speed as a decision point rather than a default. When money is needed urgently, it is tempting to choose the fastest path without examining the screen. I would compare the displayed options, review any charge or condition presented there, and ask whether the expense can wait until the ordinary payday. A few minutes of checking can prevent an avoidable cost.
A fourth useful workflow is to keep a personal record outside the app. I would note the advance date, amount, and expected impact in my banking notes or budget. That gives me a second reference if I later forget what I authorized, and it makes repeated use easier to spot. If I find myself recording advances every pay period, I would stop and reassess rather than allowing the app to become part of my normal income.
Data-sensitive moments deserve extra attention
Financial apps naturally bring sensitive moments into everyday actions: creating an account, verifying identity, connecting income information, linking a bank account, requesting money, and changing account settings. I would slow down at each of these points. The question is not only whether the app can perform the task, but whether I understand what information I am sharing and what control I have afterward.
Permissions should be reviewed in the operating system as well as inside the app. EarnIn runs on Android 8.0 or later, and the current version listed for the app is 16.57. Keeping the operating system and app current is sensible, but updates are also a good opportunity to revisit permissions and notifications. I would disable anything I do not need, while recognizing that removing a permission could affect a function that depends on it.
Notifications are another overlooked control. A finance app may send reminders or status updates, but sensitive information appearing on a lock screen can be uncomfortable. I would adjust notification previews if my phone is shared or often visible to other people. This is a small privacy choice, yet it matters because financial details can be exposed through ordinary alerts rather than through a dramatic security failure.
I would also pay attention to the final confirmation screen before requesting money. The amount, timing, destination account, and any displayed terms should be understandable before approval. If a screen feels rushed or unclear, I would leave the transaction incomplete and review the account controls first. A trustworthy experience should allow that pause without making me feel that I will lose an opportunity.
Who should use it, and who should skip it
EarnIn is most suitable for a person with regular income, a clear upcoming payday, and a temporary mismatch between when money is needed and when it becomes available. It may be particularly practical for an essential expense that cannot reasonably wait, provided the next paycheck remains sufficient for fixed commitments.
I would be more cautious if income changes from week to week, payday timing is uncertain, or the user already has several automatic payments scheduled. In those situations, an advance can make the next account balance harder to predict. Someone who is already using one advance to repay another should treat that as a warning sign and look for a broader budgeting, income, or debt-support solution instead.
I would also skip it for discretionary spending. A concert, impulse purchase, or upgrade can usually wait, and using early pay for it reduces flexibility later. The app is not a reason to stop building an emergency fund. In fact, the best long-term companion to a service like this is a small cash reserve that gradually reduces the need to move payday forward.
For users who need a larger amount, a fixed repayment schedule, or a longer-term solution, a bank loan, credit union product, employer resource, or nonprofit financial counselor may be a better fit. The right alternative depends on the problem. EarnIn addresses timing; it does not replace financial planning or solve persistent debt.
What I would check before making the first request
Before using the app, I would confirm that my employment and pay schedule are represented accurately, that the destination account is the one I intend to use, and that I can identify the next payday without guesswork. I would review every amount shown during the request process and avoid assuming that the advertised maximum applies to my own account.
I would then test my budget with the advance removed from the next paycheck. If the remaining amount cannot cover necessities, the request is too large or the timing is wrong. This is a more useful test than asking whether I can receive the money today. The real question is whether the future version of me can manage the reduced paycheck without taking another advance.
Finally, I would look through account and privacy controls before an emergency happens. Finding settings while calm is easier than searching for them when a bill is already overdue. I would make sure I know how to review activity, manage notifications, update connected information, and contact support through the available in-app paths. Clear control is part of trust, especially when the product sits close to my income.
My cautious verdict on EarnIn
EarnIn is a focused finance app with a clear use case: helping eligible users handle a short gap before their normal paycheck arrives. Its large user base, high average rating, free download, and long presence in the finance category make it worth considering, but popularity should never replace personal checking. The app earns my recommendation only when the request is planned, small, and tied to a payday I can rely on.
My strongest advice is to treat every advance as a one-time transfer from the next pay period, not as extra income. Review the amount, inspect the choices presented, protect sensitive notifications, and keep your own record of what was requested. If the same shortfall keeps returning, stop using the app as a patch and address the recurring expense or income problem directly.
For a genuine timing emergency, EarnIn can be a practical alternative to overdrawing an account or carrying a small expense on a credit card. For ongoing financial strain, uncertain income, or purchases that are not essential, I would choose a different path. Used with that boundary in mind, it is a useful tool rather than a substitute for a budget.
EarnIn: Why Wait for Payday? FAQ
What is EarnIn: Why Wait for Payday?
EarnIn is a financial app designed to give eligible users early access to a portion of wages they have already earned, rather than making them wait until the regular payday. After connecting employment and bank information, users may request an available amount and receive it through the app’s supported delivery options. Availability, limits, and eligibility can vary by user and location.
How does EarnIn determine how much money I can access?
The app calculates an available balance based on factors such as verified employment, work history, income deposits, account activity, and previous use of the service. The amount is not necessarily your full paycheck, and it may change from one pay period to another. EarnIn may also request additional verification before approving an advance or increasing your limit.
Does EarnIn charge fees or require a subscription?
EarnIn generally promotes a no-mandatory-fee model for its core cash-access service, but optional features, expedited delivery, tips, or other products may involve costs. Pricing and availability can change, so it is important to review the confirmation screen before accepting a transfer. Users should also check whether their bank or another provider applies separate fees.
How quickly will I receive money from EarnIn?
Delivery time depends on the transfer method selected, the user’s bank, account verification, and whether the request is submitted during supported processing hours. Standard delivery may take longer, while an instant or expedited option can be faster but may have additional conditions or costs. The app normally displays the expected arrival time before the request is finalized.
Is EarnIn safe to use, and what information does it require?
EarnIn uses personal and financial information to verify employment, confirm income, determine eligibility, and transfer funds. Depending on the setup, this can include identity details, bank-account information, employer data, and transaction history. Users should review the app’s privacy policy, permissions, repayment terms, and security practices, and download it only from the official Google Play Store or Apple App Store.











